
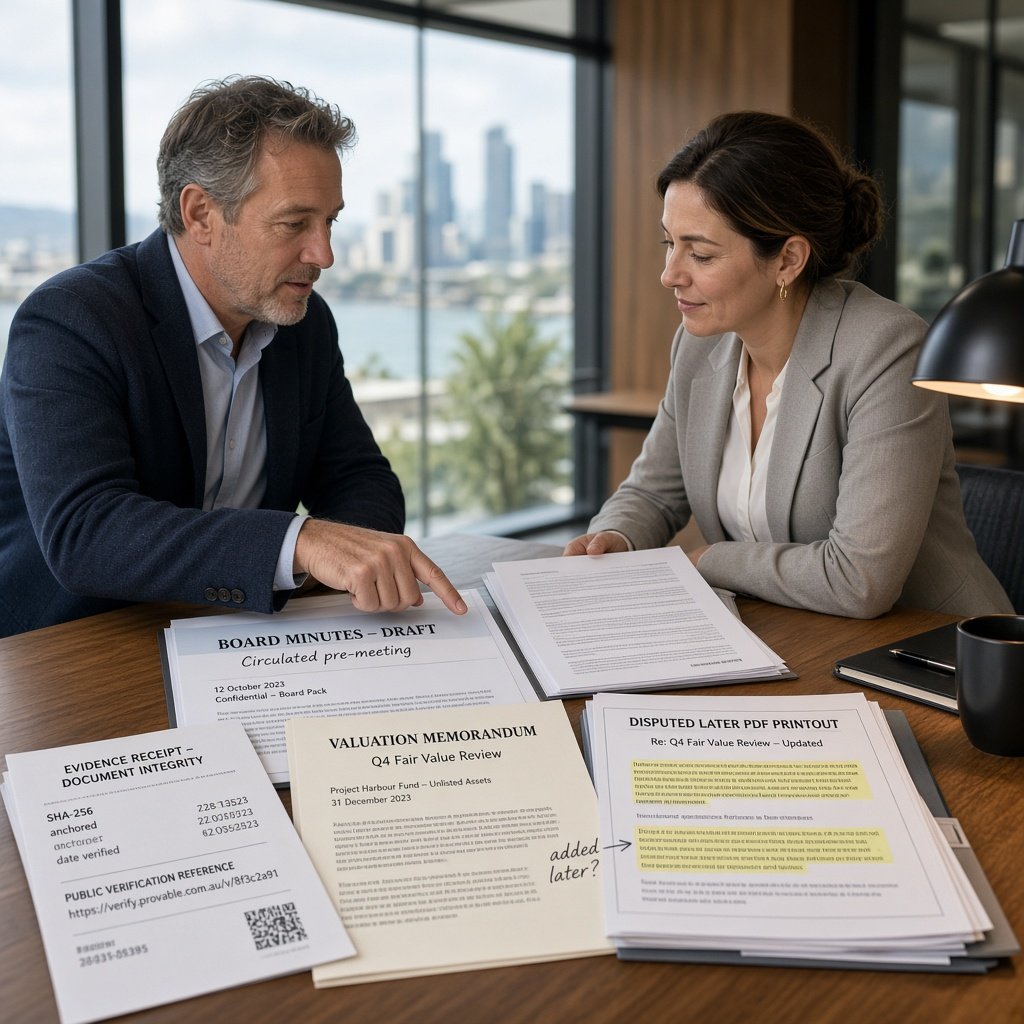
It came down to timing. A mid-sized Australian funds management group faced an audit committee crisis when disputed board papers appeared to show that a valuation methodology had been approved only after a sharp quarter-end markdown. The professional risk was severe: possible misleading disclosure to investors, regulator scrutiny, partner qualification of accounts, and personal exposure for directors and the CFO. The outcome turned on board minutes timestamp verification, which established when the relevant draft and final approval records existed and whether they had been altered. A blockchain timestamp attached to the files before the dispute gave the firm defensible evidence that the core documents had existed in a specific form at a specific time.
Table of Contents
The valuation dispute that escalated
Southern Harbor Capital, a fictional private credit and alternatives manager based in Sydney, had just completed a difficult reporting cycle. One portfolio company had missed earnings, forcing debate over a material fair-value adjustment. The investment team said the board valuation paper had been circulated in time, reviewed by the valuation committee, and reflected in the quarter-end pack before investor reporting was finalised. Two months later, during external audit fieldwork, a conflicting PDF surfaced from an internal mailbox archive. That version carried wording suggesting the rationale for the markdown had been expanded after quarter-end, raising suspicion that the final board minutes had been cleaned up to match a decision already under challenge.
The concern was not academic. If management had revised minutes or explanatory memoranda after the valuation decision and then presented them as contemporaneous records, the dispute could affect audit conclusions, limited partner trust, side-letter obligations, and future capital raising. The firm needed a reliable way to show whether its governance documents were authentic in both content and timing. The compliance lead had previously implemented financial document verification for regulated finance teams for key committee papers, subscription materials, side letters, and valuation memoranda. That decision became central once the authenticity issue widened.
Why timing mattered to the audit committee
In regulated and high-value commerce, timing often determines whether a document is evidence of process or evidence of reconstruction. For boards, auditors, and regulators, it matters whether a file existed before approval, before disclosure, before settlement, or only after challenge.
A blockchain timestamp is a dated cryptographic record linked to a specific file hash. A file hash is a unique digital fingerprint generated from the file contents.
Proof of existence, proof of time, digital file integrity, and blockchain evidence work together to show that a specific electronic record existed in a specific state at a specific moment.
Digital file integrity means the contents have not changed since the fingerprint was created. Proof of time means the file fingerprint can be tied to a verifiable point in time.
In simple terms, the fund manager needed to show that its board papers were not backfilled after the valuation argument emerged.
That was especially important because the disputed records sat at the intersection of governance and investor disclosure. Auditors were assessing whether the markdown had been supported by contemporaneous analysis. The board chair was assessing whether the committee had been properly informed before sign-off. And the general counsel was assessing whether any later edits could be characterised as innocent formatting changes or substantive narrative alterations. In finance, that distinction can carry contractual, regulatory, and reputational consequences.
What the timestamped records showed
The compliance team had used TimeBinder on the original valuation memo, the board pack index, and the meeting minutes draft circulated the day before the committee met. Files were SHA-256 hashed locally in the browser, and only the cryptographic hash was anchored to Bitcoin. The files themselves never left the device. For the most sensitive quarter-end documents, the firm had selected ASAP Priority, which meant the resulting evidence could later be checked independently on a public explorer rather than requiring bundled verification through the provider.
When the dispute surfaced, the team retrieved the stored verification receipts and compared three documents: the pre-meeting valuation memorandum, the board minutes draft, and the version eventually included in the signed governance pack. The hashes showed that the pre-meeting memo and the draft minutes matched the versions TimeBinder had timestamped before quarter-end. The conflicting PDF from the mailbox archive did not match those fingerprints.
The discrepancy turned out to be significant. The archived PDF contained two inserted paragraphs expanding the narrative around management’s confidence in the revised valuation methodology. Those additions were not merely typographical. They strengthened the appearance that the board had considered a wider range of downside scenarios before sign-off. Because the disputed PDF produced a different hash, it could not be the same file as the version anchored earlier.
The auditors then used the receipt data and checked the public evidence path through blockchain.com/explorer. The firm also documented the process against its internal controls and retained the matching reports produced through blockchain file verification. That gave the audit committee an independent, repeatable way to assess whether the questioned file had existed in that exact form at the relevant time.
What a blockchain timestamp proves
A blockchain timestamp proves that a particular file fingerprint existed no later than the time it was anchored to the blockchain. If a later file produces the same hash, it is evidence that the contents are the same as the earlier timestamped version. If it produces a different hash, it is evidence that the contents are different.
What it does not prove is who authored the file, whether the underlying statements were true, or why changes were made. It proves existence, timing, and integrity of the specific digital file presented for comparison. That narrow evidentiary function is precisely why it was useful here: the dispute was about whether governance wording had been changed after the fact, not whether the valuation debate itself had been difficult.
Because the records had been anchored before the challenge emerged, the evidence had more credibility than a reactive internal assertion. The board could distinguish between contemporaneous records and later reconstructed versions. The auditors could test file integrity without relying solely on email metadata or subjective witness recollection. And the fund manager could show that its control environment around sensitive documents was stronger than the disputed archive version suggested.
How the dispute was resolved
Once the mismatched file was isolated, the firm investigated its provenance. A junior executive assistant had combined comments from two separate drafts while preparing a briefing copy for an internal governance review after quarter-end. That blended PDF was then saved back into a folder later captured by the mailbox archive export. No one had intended to falsify the board record, but the resulting document created exactly that appearance because it mixed contemporaneous text with later explanatory language.
The timestamped evidence allowed the audit committee to separate process failure from misconduct. The committee concluded that the official pre-meeting memo and circulated draft minutes were authentic contemporaneous documents, while the archive PDF was a later composite created for internal administrative use. The external auditors required remediation of document control procedures but did not qualify the valuation process on the basis of fabricated approval records. Investor reporting was supplemented with a governance note to explain the chronology. Most importantly, the directors avoided a much more serious inference that the fund had rewritten its approval trail after the markdown became contentious.
Timestamped records reduce evidentiary uncertainty in high-risk disputes.
Lessons for regulated finance teams
This case illustrates why finance teams should not reserve timestamping for contracts alone. Board packs, committee minutes, valuation memoranda, disclosure drafts, side letters, redemption notices, and exception approvals can all become high-stakes evidence. Where multiple near-final drafts circulate under time pressure, file-level proof of existence can be more dependable than folder dates, printouts, or recollection.
The practical lesson was simple: timestamp the records that define who knew what, when they knew it, and what exact wording supported critical decisions. In regulated environments, those questions can shape audit outcomes, remediation scope, reporting obligations, and senior accountability. This fictional case study is purely illustrative of what is happening in business right now. This could happen to your business.
Frequently Asked Questions
- What was the core issue in this dispute?
The core issue was document timing. Auditors needed to know whether valuation-related board records existed before quarter-end approval or were revised after the dispute emerged.
- What does a blockchain timestamp prove?
A blockchain timestamp proves a file fingerprint existed at or before a verifiable time. It helps show whether a presented document matches the earlier version exactly.
- What is proof of existence?
Proof of existence shows a specific digital file existed at a certain time.
- Why not rely only on email dates or folder metadata?
Metadata is limited evidence. A blockchain timestamp is stronger because file movement, copying, exports, and relabelling can confuse ordinary system dates without proving content integrity.
- Did the timestamp decide whether the valuation itself was correct?
The timestamp did not decide valuation correctness. It showed which governance documents were contemporaneous and which file version was created later, narrowing the dispute to process and control.







