
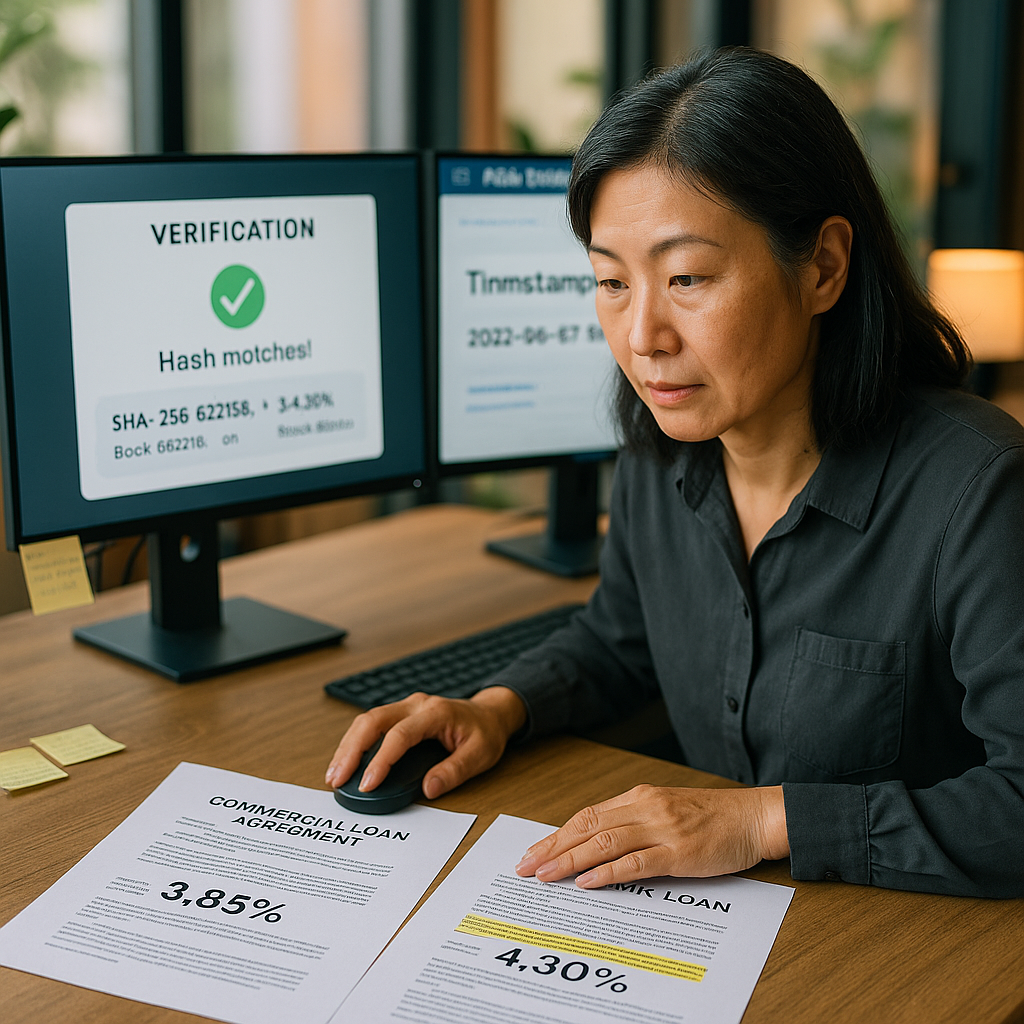
A contested loan amendment placed a regional lender at regulatory and litigation risk. In this fictional but realistic case study, a borrower alleged that interest terms had been altered after execution, exposing the bank to potential ASIC scrutiny, civil action, and reputational damage. The matter was resolved when financial document verification supported by a blockchain timestamp proved the precise timing and integrity of the original agreement.
Table of Contents
Background of the Dispute
Harbourline Capital, a mid-sized Australian commercial lender, had negotiated a $14 million facility with a property development firm. Two weeks after settlement, market rates shifted sharply. The borrower later claimed that a revised interest clause—raising the margin by 45 basis points—had been inserted after the final board-signed PDF was circulated.
The borrower’s legal representatives produced what appeared to be an earlier version of the facility agreement. The formatting was identical. The signature page matched. Only the interest schedule differed.
The accusation was serious. If Harbourline had modified the agreement post-signature, it could constitute misleading conduct, breach of lending obligations, and potential regulatory reporting failures.
Internally, the credit team insisted that the higher margin had been agreed during final negotiations. However, email threads were ambiguous. Attachments had similar file names. The document management system showed upload dates, but those timestamps were editable by administrators.
The dispute turned on one question: which version existed first?
Why Timing Matters in Regulated Lending
Document timing is critical in high-value financial transactions because lending decisions, pricing, and risk disclosures must be demonstrably fixed at a specific moment before execution.
Regulators expect institutions to maintain reliable records demonstrating that borrowers received accurate and complete terms prior to acceptance. Courts examine metadata, correspondence history, and system logs when authenticity is disputed.
In simple terms, if a lender cannot prove when a contract version existed, it may struggle to defend its legitimacy.
In regulated environments, uncertainty around document sequencing can expose firms to allegations of post-dated edits, misrepresentation, or unfair contract variation. Even minor discrepancies in timing can undermine enforceability.
Financial document verification provides an evidentiary framework for demonstrating that a specific digital contract existed in a specific state at a specific time.
Understanding Blockchain Timestamping
A blockchain timestamp is a cryptographic record anchoring a document’s unique hash to a public blockchain at a specific block height and time.
Files are hashed locally in the user’s browser using SHA-256. Only the cryptographic hash is anchored to the Bitcoin blockchain.
Files are never uploaded and remain on the user’s device.
A timestamp is a verifiable marker indicating when a specific digital fingerprint of a file was recorded.
Digital file integrity refers to the assurance that a file has not been altered since its hash was generated.
Proof of existence confirms that a specific digital file was in existence at or before the recorded timestamp.
Proof of time establishes that the document’s hash was embedded in a blockchain transaction at a particular moment.
A blockchain provides decentralised, append-only recordkeeping resistant to retroactive modification.
Proof of existence, proof of time, digital file integrity, and blockchain verification together establish objective evidence that a specific file version existed at a recorded moment without alteration.
What a blockchain timestamp proves is limited but powerful: it demonstrates that the exact cryptographic hash of a file was recorded on the blockchain at a certain time, and that any subsequent modification would generate a different hash and fail verification.
Implementation at the Bank
Six months before the dispute, Harbourline’s compliance officer had introduced financial document verification for regulated lending agreements. Final execution copies of facility agreements were timestamped immediately after board approval.
The bank selected the “ASAP Priority” option for high-value facilities. Only the “ASAP Priority” timestamping option allows independent verification via public blockchain explorers. The “Pooled Priority” option relies on bundled verification requiring the TimeBinder platform.
When the loan in question was finalised, the executed PDF was hashed in the credit manager’s browser. Only the resulting SHA-256 hash was anchored to Bitcoin. The original file never left the bank’s system.
When the dispute arose, the compliance team retrieved the archived PDF and re-ran verification. The hash matched the previously recorded value. Using blockchain.com/explorer, they independently confirmed the transaction containing the hash reference at a date and time two days before settlement.
The borrower’s alternative version produced a different hash. It could not be reconciled with the earlier blockchain record.
For internal assurance, the bank also documented the process through its governance committee and cross-referenced procedures outlined in its blockchain file verification policy guidance.
How the Evidence Resolved the Allegation
The borrower’s legal team initially questioned whether the bank could have timestamped a modified document retroactively. Independent review clarified that the blockchain entry predated the alleged alteration and could not be backdated without rewriting the public chain.
The critical detail was sequence. The timestamp preceded both the settlement date and the borrower’s claimed “original” version.
Presented with independently verifiable evidence, the borrower’s advisers withdrew the allegation of post-signature modification. Negotiations shifted from misconduct claims to commercial refinancing discussions.
No regulator inquiry was opened. No litigation was filed. The bank’s board received a report confirming that the documentation trail met evidentiary standards.
The resolution did not depend on internal logs or employee testimony. It relied on objective cryptographic verification.
Lessons Learned
Timestamped records reduce evidentiary uncertainty in high-risk disputes.
First, high-value financial agreements should be timestamped at the moment they become authoritative versions. Drafts and negotiations may evolve, but execution copies must be fixed in time.
Second, independent verification strengthens credibility. The ability to confirm a blockchain timestamp through a public explorer removed any perception of internal manipulation.
Third, financial document verification is most effective when integrated into workflow rather than used reactively after a disagreement arises.
Finally, blockchain-based proof does not replace sound governance, but it significantly enhances defensibility when authenticity is challenged.
Frequently Asked Questions
- What does a blockchain timestamp prove in lending disputes?
A blockchain timestamp proves that a specific document hash existed at a certain time and has not changed since that record.
- How is proof of existence defined?
Proof of existence is cryptographic evidence that a specific digital file existed at or before a recorded timestamp.
- Are the original loan documents uploaded to the blockchain?
No original documents are uploaded. Only a SHA-256 hash is anchored, while files remain on the user’s device.
- Can the verification be checked independently?
Yes, with the ASAP Priority option. The blockchain timestamp can be confirmed using a public blockchain explorer without relying on the platform.
- Why is financial document verification important for regulators?
It strengthens evidentiary reliability. A verified blockchain timestamp helps demonstrate digital file integrity and proper sequencing of executed agreements.







