
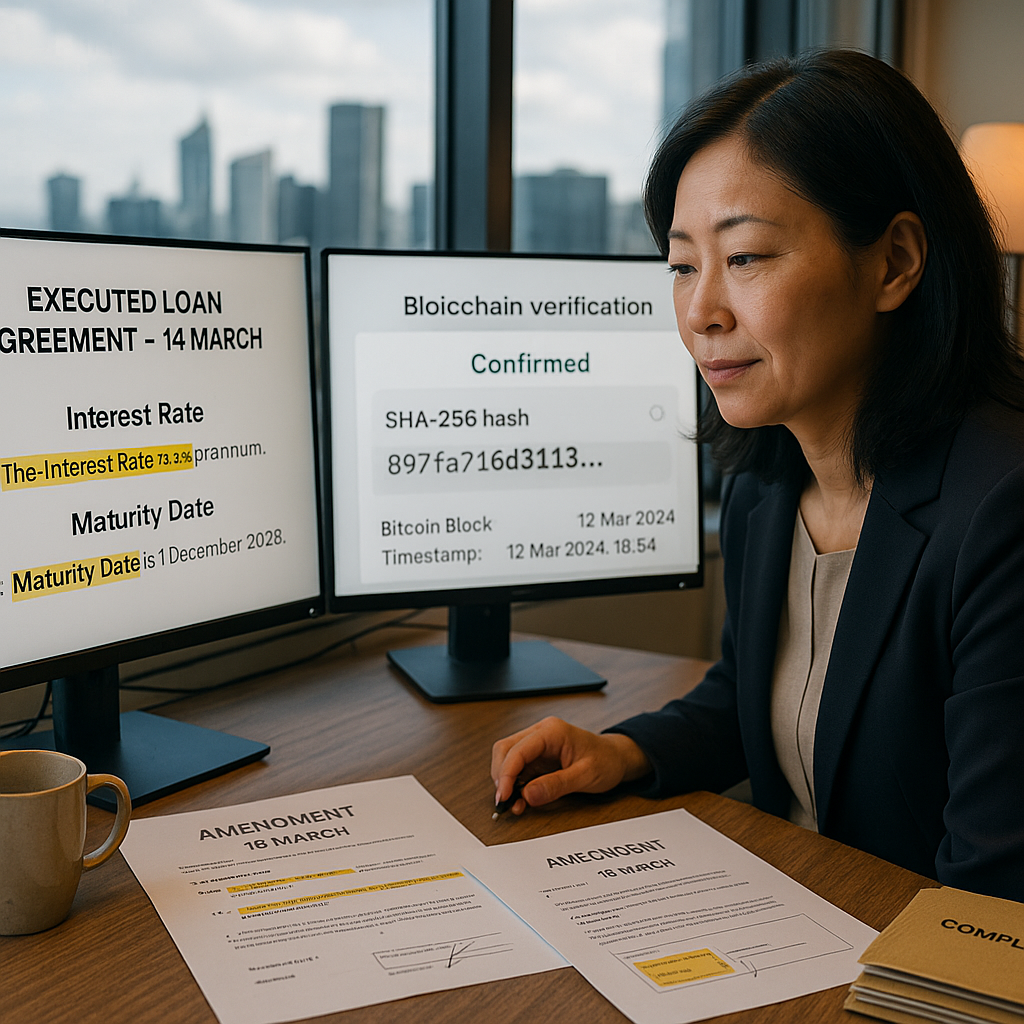
A signed loan amendment appeared to rewrite a company’s repayment obligations. In this fictional but realistic case study, a mid-market lending firm faced a borrower claim that revised terms had been formally approved months earlier, exposing the lender to regulatory scrutiny and potential financial loss. The dispute centred on which version of the agreement was authentic. The professional risk included breach of lending standards, reputational damage, and possible enforcement action. The outcome turned on financial document verification and a blockchain timestamp that proved when the original contract was finalised and that it had not been altered afterward.
Table of Contents
Background of the Dispute
Harbourline Capital, a Sydney-based private lender, had extended a $12 million facility to a property development group. The executed loan agreement included a fixed interest rate and a clear repayment schedule. Six months later, as market conditions shifted, the borrower produced what appeared to be a countersigned amendment reducing the interest rate and extending the maturity date.
The lender’s relationship manager denied approving the change. However, the borrower supplied a PDF copy bearing what looked like legitimate digital signatures and a date consistent with prior negotiations. If the amendment were genuine, Harbourline would be obligated to honour less favourable terms and explain the variation to its credit committee and external auditors.
The firm had implemented financial document verification for regulated lending environments precisely to address such risks.
Regulatory and Financial Exposure
Under Australian responsible lending and corporate governance standards, maintaining accurate and contemporaneous records of executed agreements is mandatory. Inconsistent documentation can suggest weak internal controls.
If regulators concluded that Harbourline had informally renegotiated terms without proper approval, the company could face compliance reviews, penalties, and investor concern. Internally, the credit committee questioned whether an authorised signatory had mistakenly approved the amendment.
The dispute therefore extended beyond a commercial disagreement. It evolved into a question of documentary authenticity with professional accountability implications.
Understanding Timestamp Evidence
A blockchain timestamp is a cryptographic record anchoring a document’s hash to a public blockchain at a specific point in time.
Digital file integrity refers to assurance that a file has not been altered since a defined reference moment.
Proof of existence establishes that a specific digital file existed at or before a recorded time.
Proof of time confirms the precise moment a cryptographic hash was committed to an immutable ledger.
A timestamp is a verifiable record associating data with a particular date and time.
Proof of existence, proof of time, digital file integrity, and blockchain verification together form a cryptographic evidentiary framework linking a specific file hash to a publicly recorded moment without revealing the file’s contents.
In simple terms, the system allows a lender to demonstrate that a particular version of a contract existed at a defined date and has not changed since.
How the Verification Process Worked
When the original loan agreement was executed, Harbourline’s compliance officer used TimeBinder to create an evidentiary record. Files are hashed locally in the user’s browser using SHA-256. Only the cryptographic hash is anchored to the Bitcoin blockchain. Files are never uploaded and remain on the user’s device.
For this agreement, the firm selected the “ASAP Priority” option, enabling independent verification via public blockchain explorers. The hash was recorded and later verifiable through blockchain.com/explorer. The alternative “Pooled Priority” option relies on bundled verification requiring the TimeBinder platform.
Months later, when the borrower produced the disputed amendment, Harbourline generated a SHA-256 hash of the original executed agreement stored in its records. The compliance team then performed blockchain file verification to compare the stored hash against the blockchain record.
The blockchain timestamp predated the borrower’s alleged amendment by four days. More importantly, hashing the borrower’s version produced a different cryptographic value, confirming it was not identical to the originally timestamped file.
Why Timing Matters in Lending
In regulated financial services, document timing determines enforceability, reporting accuracy, and accountability. Credit approvals must align with board delegations. Amendments require documented authority and updated risk assessments.
A blockchain timestamp proves that a specific cryptographic hash corresponding to a digital file was recorded on the Bitcoin blockchain at a defined block height and time, creating independently verifiable evidence that the file existed in that exact state at or before that moment.
When disputes arise, demonstrating that a document existed in a precise form at a specific time can determine whether a variation was authorised, backdated, or fabricated. Without objective time anchoring, organisations rely on internal logs or contested email trails, which may be challenged.
In high-value lending, even minor discrepancies in timing can affect interest calculations, covenant compliance, and investor disclosures. Accurate temporal records reduce ambiguity when negotiations overlap with execution formalities.
Resolution and Professional Consequences
After confirming that the blockchain timestamp for the original agreement preceded the borrower’s purported amendment, Harbourline requested the borrower provide evidence of independent timestamping for their version. None was available.
The lender’s legal counsel presented the hash comparison and public verification record to the borrower’s representatives. Because the “ASAP Priority” option allows independent validation without platform dependency, the evidence was demonstrable using a public blockchain explorer.
Confronted with cryptographic proof that the lender’s version had been fixed in time before the amendment’s alleged execution date, the borrower withdrew its claim. Subsequent internal investigation suggested the borrower had circulated a draft amendment during negotiations but never obtained authorised countersignature.
The dispute concluded without litigation. Harbourline documented the incident for its audit committee and updated its procedures to require timestamping for all executed amendments, not just original agreements.
Lessons Learned
Timestamped records reduce evidentiary uncertainty in high-risk disputes.
This case illustrates that financial document verification is not merely administrative. It forms part of a defensible control framework in environments where regulatory scrutiny and contractual precision intersect.
By anchoring only the document hash rather than the file itself, the firm preserved confidentiality while obtaining independently verifiable proof. The use of a blockchain timestamp shifted the discussion from conflicting recollections to objective cryptographic evidence.
For senior executives and compliance officers, the lesson is procedural discipline. Agreements, amendments, side letters, and credit approvals all benefit from immediate timestamping at execution. Delayed verification weakens evidentiary clarity.
In an industry where trust and documentation underpin capital allocation, proof of time and proof of existence provide measurable safeguards against costly disputes.
Frequently Asked Questions
- What does a blockchain timestamp demonstrate in a loan dispute?
A blockchain timestamp demonstrates that a specific document hash existed at a defined moment on the blockchain. It provides independently verifiable proof of time and supports digital file integrity in contested agreements.
- How does financial document verification reduce regulatory exposure?
It strengthens evidentiary records. By confirming execution timing and document integrity, financial document verification helps demonstrate compliant internal controls during reviews or investigations.
- Are the original loan documents uploaded to the blockchain?
No files are uploaded. Only the SHA-256 hash is recorded on the blockchain, while the original documents remain on the user’s device.
- What is proof of existence?
Proof of existence is cryptographic evidence that a specific digital file existed at or before a recorded time.
- Can third parties independently check the timestamp?
Independent verification is possible with the ASAP Priority option. The blockchain timestamp can be checked using a public explorer, confirming proof of time without relying on internal systems.







